
#Tata Capital LTD #IPO #Review 🏦 Tata Capital : India's 3rd Largest & most diversified NBFC Backed by the TATA legacy ✨ 📕#RHP Deep Dive : Complete analysis of its RHP & Key data points 📖 A Thread 🧵
🔷 IPO Details: Open: 6 to 8 October 2025 Price: ₹ 326 Size: ₹15,511.9 Cr (Fresh ₹6846 Cr + OFS ₹8665.9 Cr) 🔷 Utilisation of IPO fund: ➡️ Augmenting the company's Tier-I capital base to meet future capital requirements and support business & asset growth = 6846 Cr
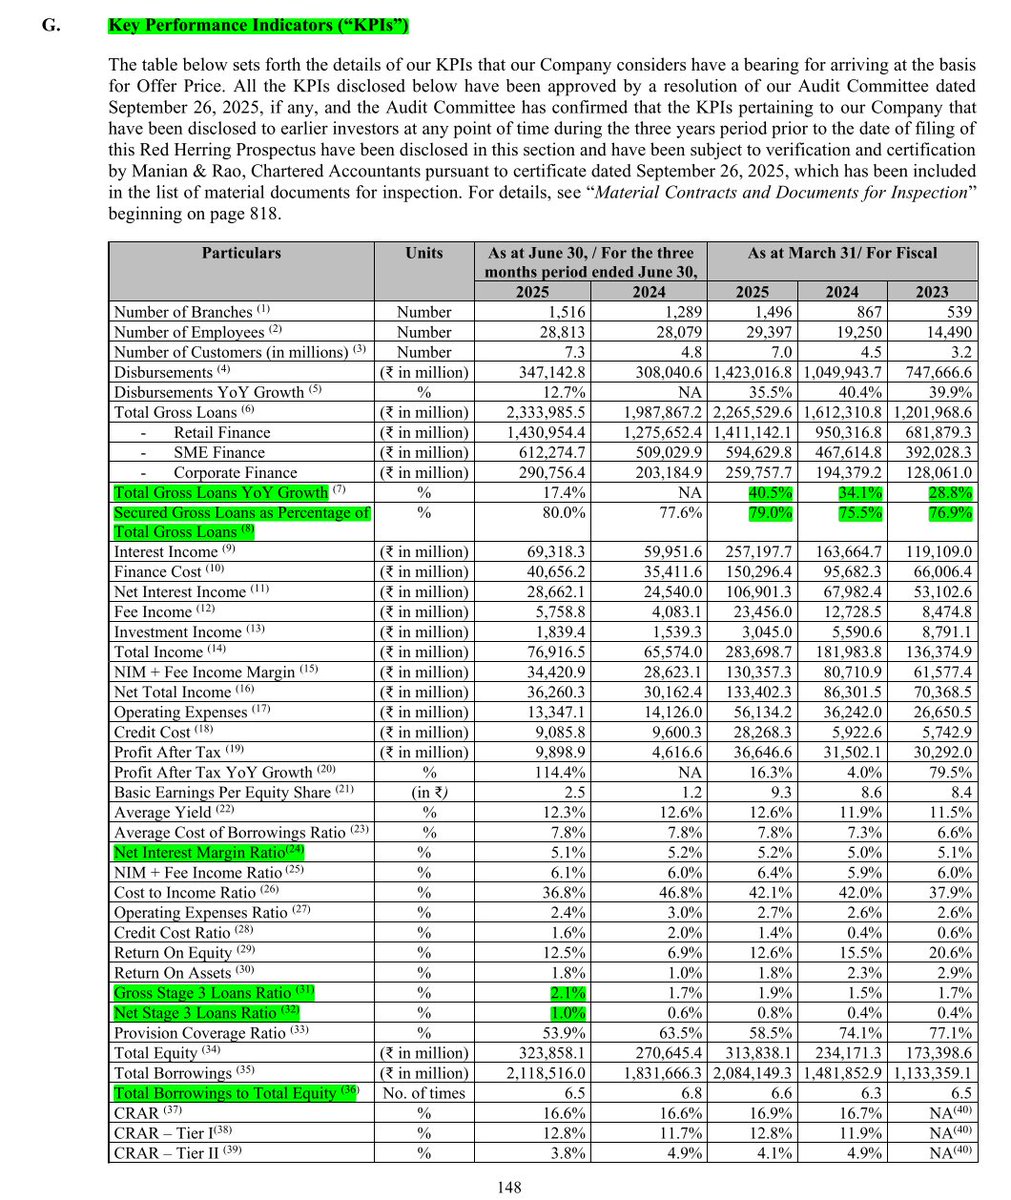
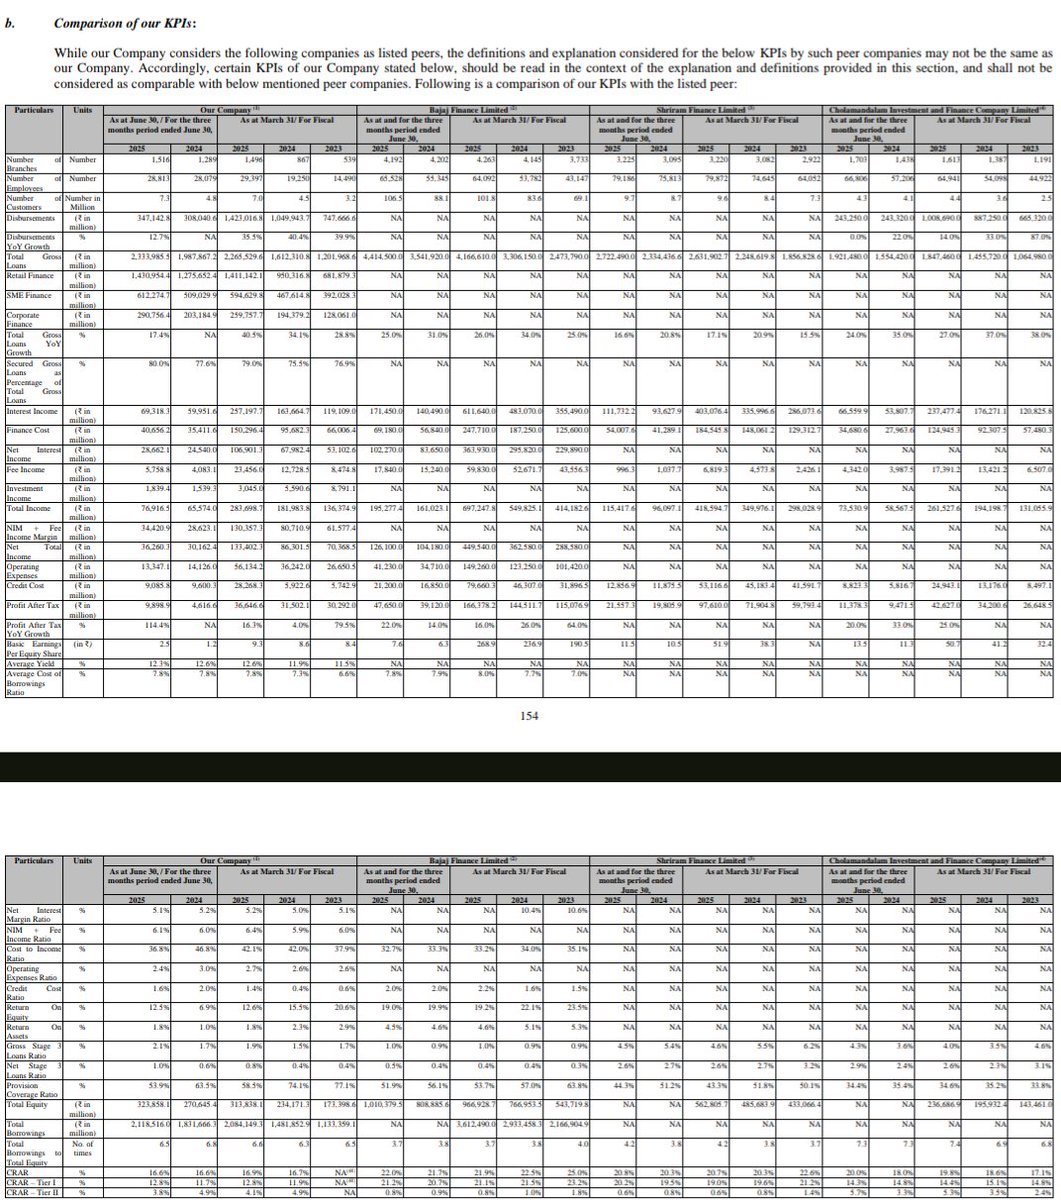
🔷 KPIs: ▫️ROE: 12.6% ▫️ROA: 1.8% ▫️Net Interest Margin (NIM): 5.1% ▫️Total Gross Loans YoY Growth: 40.5% ▫️PAT YoY Growth: 16.3% ▫️Gross NPA: 2.1% & Net NPA: 1% (as of June 30, 2025) ▫️Total Borrowings to Equity: 6.5x
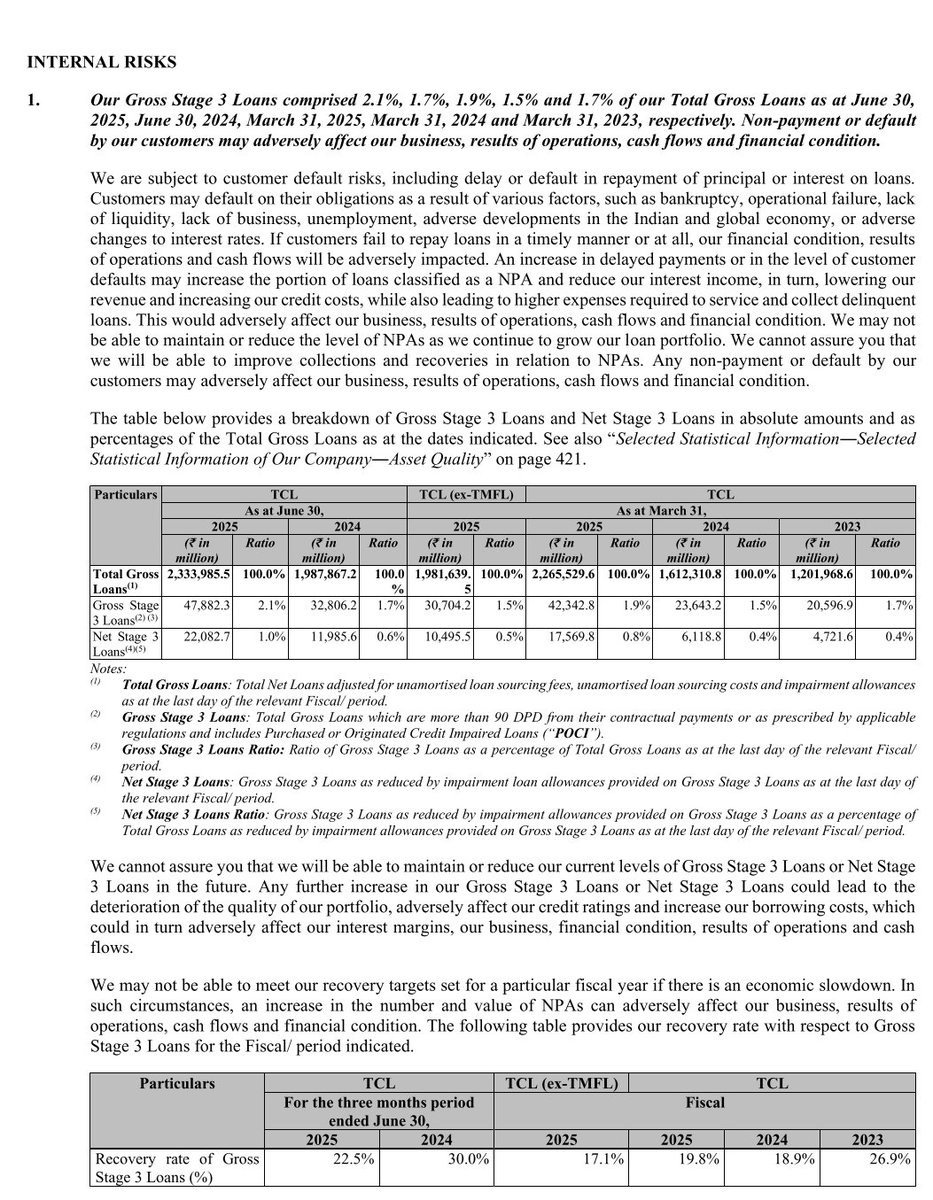
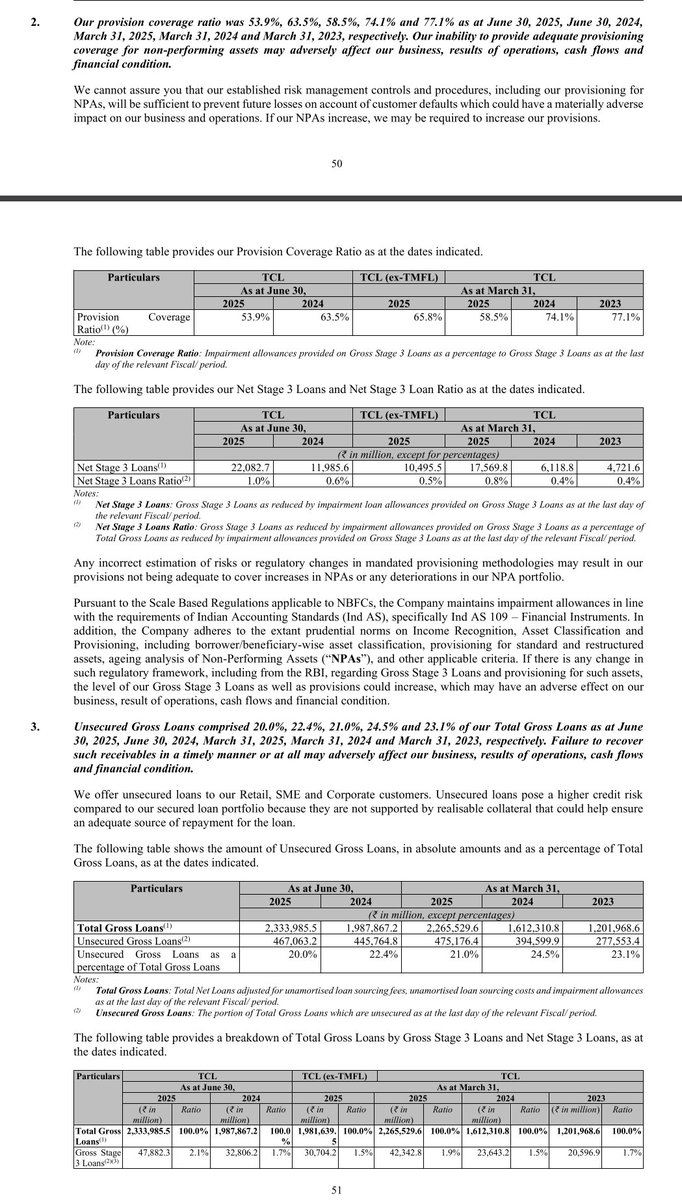
🔷 Risk Factors: ➡️Business is directly linked to the India's macro-economic environment Any downturn could increase defaults & reduce loans demand ➡️Non-payment or default by customers & failure to recover is an inherent risk for NBFCs that could adversely affect the business

➡️Being in a highly regulated industry, changes in laws & regulations by the RBI and other bodies could adversely affect business operations & profitability. ➡️Repo rate changes by RBI can affect NIMs ➡️ Intense competition from banks , other NBFCs & Fintech players

🔷 Peer Comparison: ➡️ P/B Ratio: Tata 3.98 (Pre IPO at ₹82 BV) HDB 3.9 Bajaj Finance 6.5 Cholamandalam 5.7 ➡️NIM Tata 5.1% HDB 7.7% Bajaj Finance: 9.7% Chola 7.8% ➡️Net NPA Tata 1% HDB 1.1% Chola 2.9% Bajaj Finance 0.5% Very robust & reasonable financials ✅

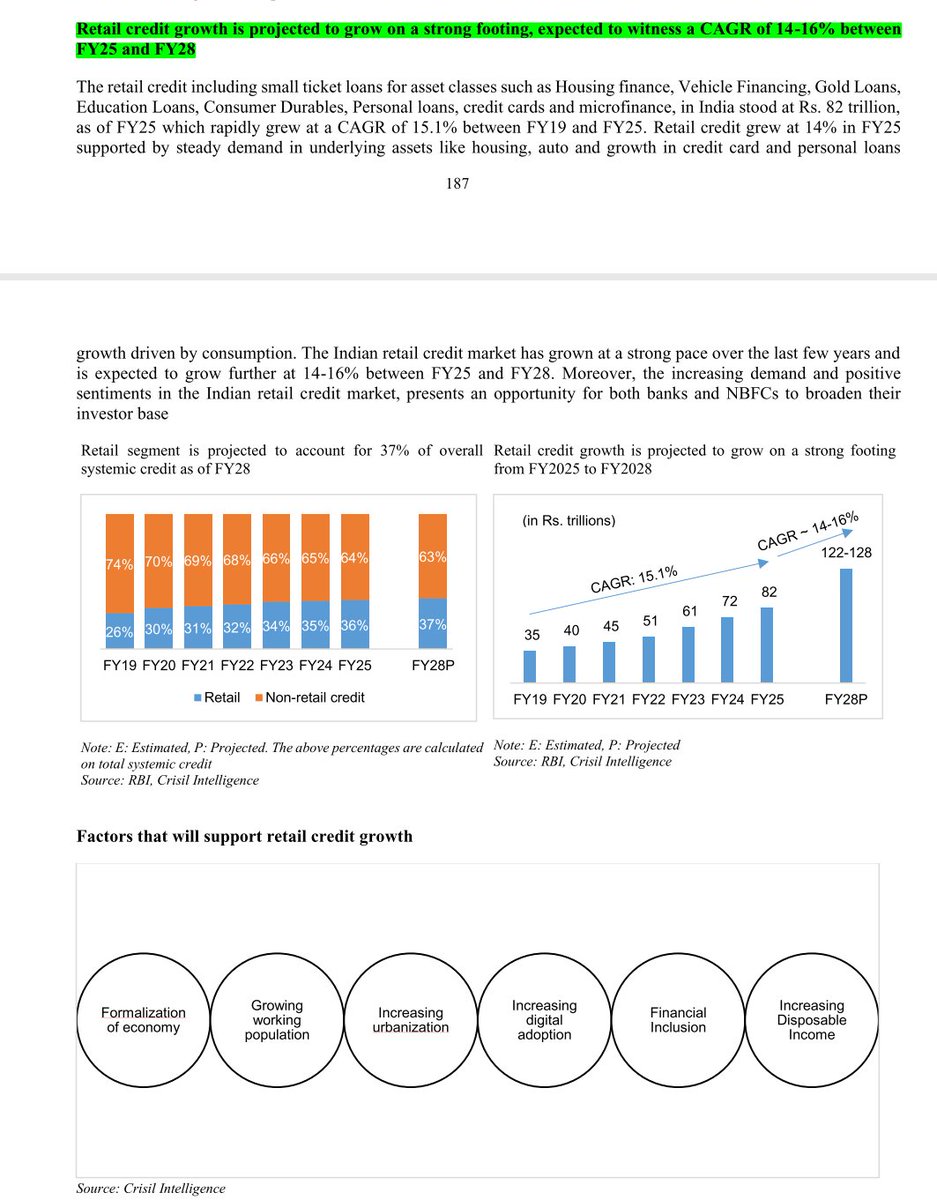
🔷 Industry Overview: ➡️Indian NBFC sector is in a high-growth phase; NBFC credit to grow at 15-17% between FY25 to 28 outpacing the banking sector. This growth is fueled by the retail segments - housing, vehicle & personal loans which is expected to grow at a CAGR of 14-16%

➡️ Digital Transformation DPI in India have revolutionized lending Efficiency in Catering to Credit Pan-India in Remote / Tier 2+ Regions via Digital Lending Phygital Network Key for Distribution + Underwriting ➡️ Favorable Government Schemes like PMAY for affordable housing


🔷 Company Overview & Key Strengths: ➡️Flagship Tata Group Company: one of India's most trusted & valuable brands ➡️Third Largest diversified NBFC in India ➡️Diversified & Strong loan book: 80% Secured loans, Offers >25 products in Retail, SME & Corporate verticals, including-

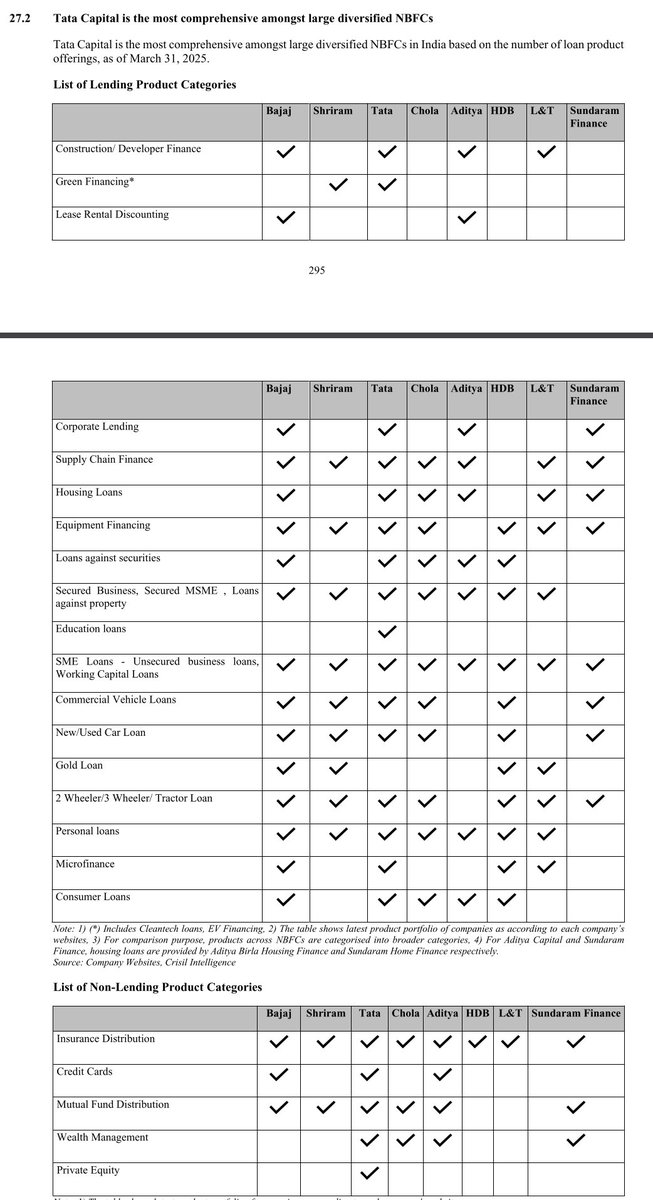
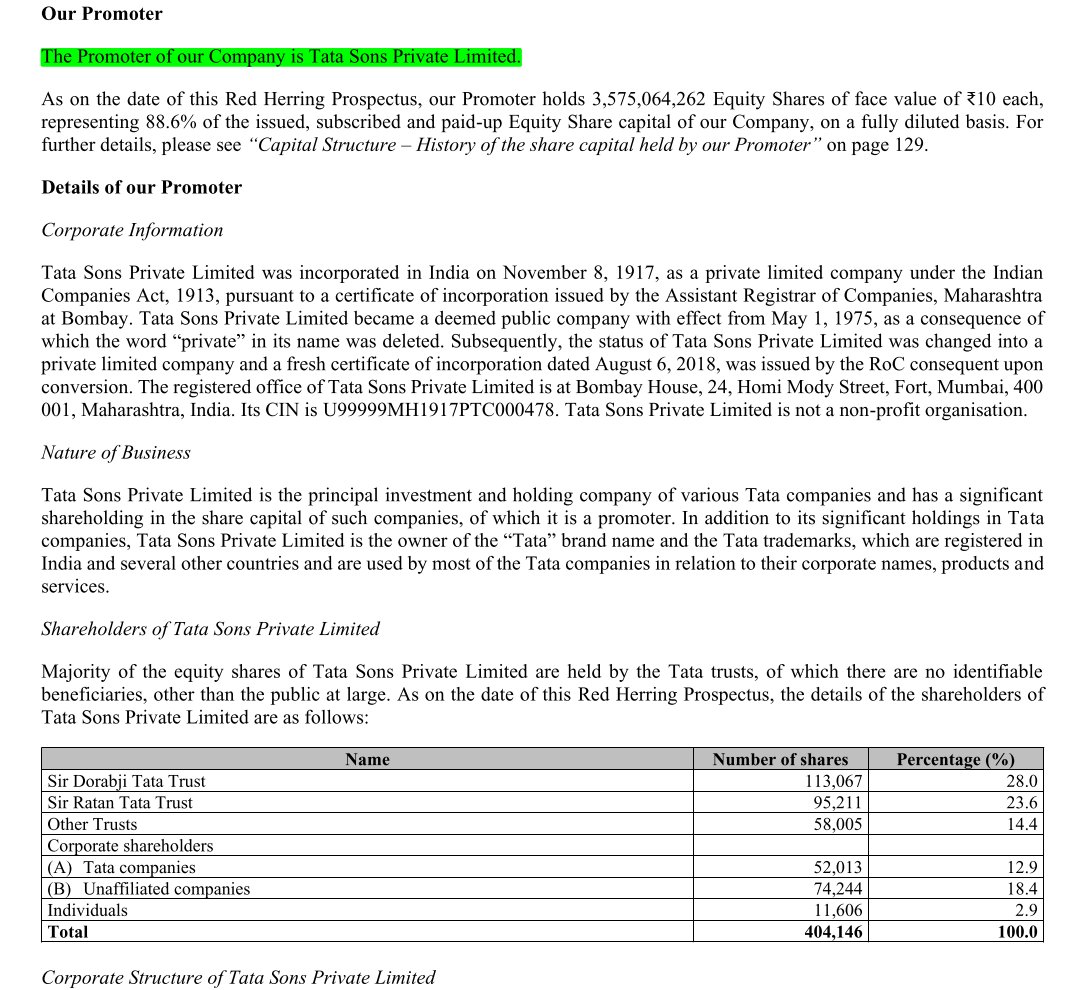
-in housing finance through subsidiary TCHFL ➡️Holds the highest credit rating of 'AAA' from domestic agencies & An investment grade 'BBB' rating from S&P Global. 🔷 Promoter & BOD ➡️ Tata sons (held by tata trusts) is promoter of the company ➡️88.6% promoter holding Pre IPO
🔷 Consolidated Financial Summary: ➡️ From FY 23 ➡️ FY25: Revenue: ₹13,637 Cr ➡️ ₹28,369 Cr 44% CAGR PAT : ₹3029 Cr ➡️ ₹3665 Cr Excellent Revenue growth based on high growth of the loan book PAT growth is moderate as opex & finance costs increased

🔷 Operating Cash Flow: For banking Cash Flow viewed differently A negative OCF is often a sign of growth not distress This happens when cash disbursed for new loans (operating outflow) is greater than cash collected from loan repayments Tata Capital's -ve OCF of ₹29872 Cr -
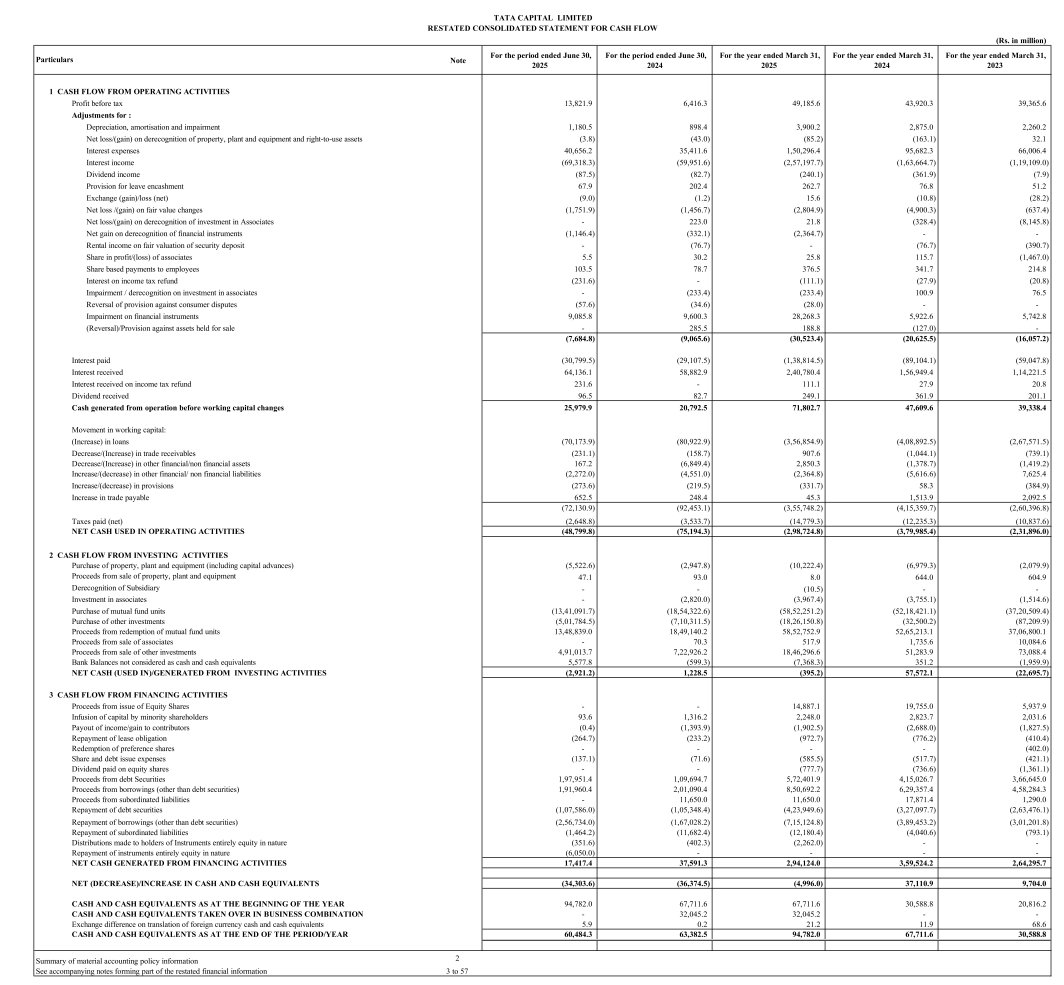

-reflects its aggressive loan book growth 🔷 Key take ✅ Excellent financial growth & asset quality coupled with reasonable P/B ❌ Modarate NIMs & intense competition 🔷Rating 8/10 🙏 Thanks for Reading Follow @EngineerStockks for more such analysis & Retweet This🧵 The 🔚