
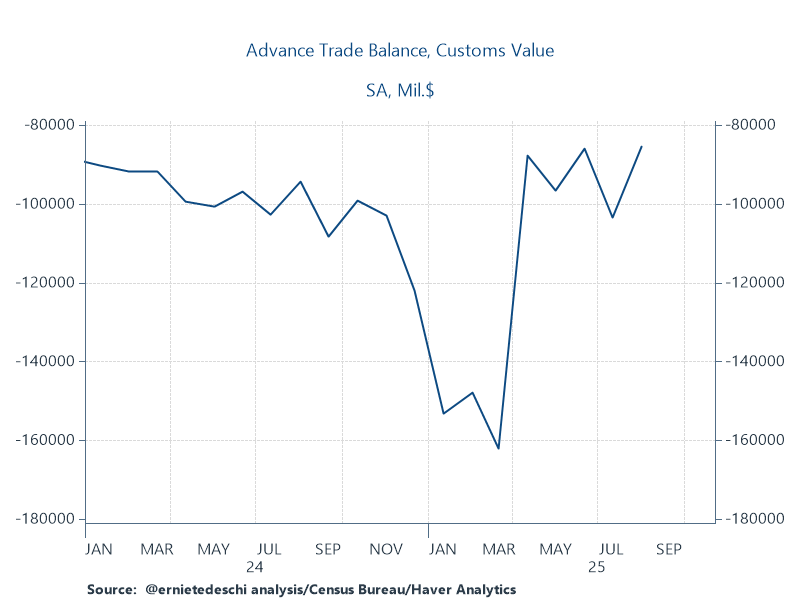
More accurate to say "Given dollar weakness YTD & monthly Census trade data, tariffs are probably modestly reducing the trade deficit **right now**, but past experience is no guarantee of future performance" etc. If USD starts appreciating, effect will quickly become ambiguous.
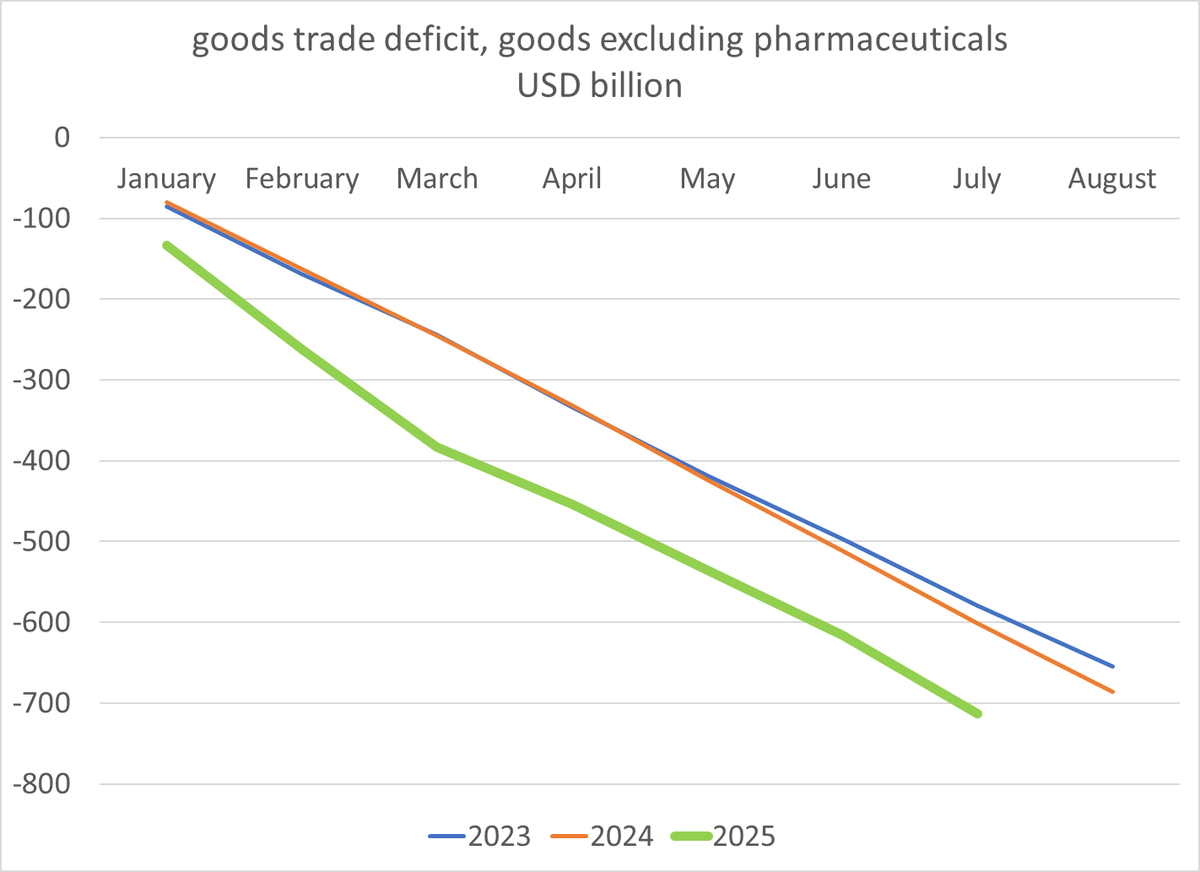
@ernietedeschi Actual trade deficit is tracking wider in 2025 (need August details to fill that data point so need shutdown to end) ... AI spending has meant more imports of electronics. Very clear in data
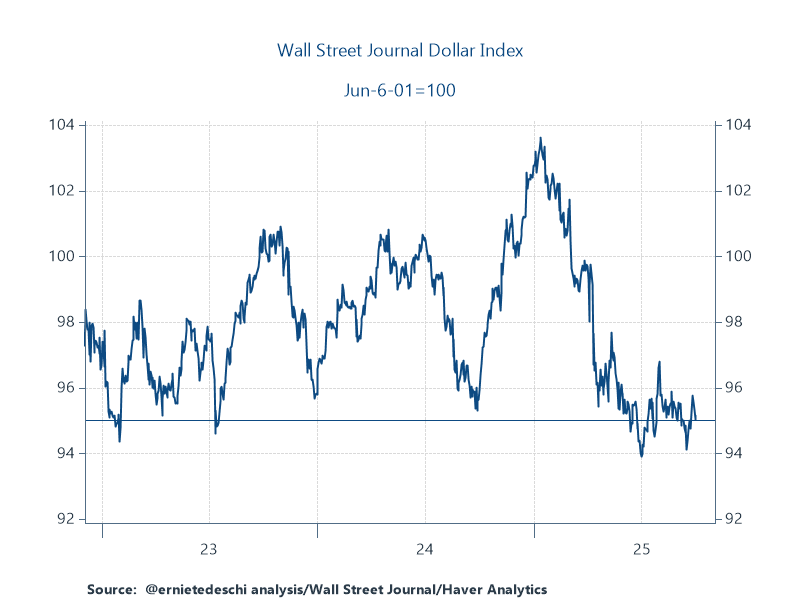
@ernietedeschi And the dollar isn't weak! the initial "Trump trade" rally wasn't sustained ... so the dollar didn't strengthen further from its strong 23/24 level. but still have a dollar at levels that historically reduced exports v GDP in a standard model. Just sayin'
@Brad_Setser So I was looking at spot monthly trade balance values, which show smaller deficits than the same months last year. But I get what you're saying, which is fair: on a cumulative basis including the wider deficits earlier in the year, YTD is tracking larger deficits. 1/2
@Brad_Setser On USD, I disagree more, at least rel to recent history. Yes, weakness is less pronounced if you ignore the post-Sep 2024 rally, but it's still below the 2024 trough & only barely above the troughs in 2023. I'm more open to the argument that USD was overvalued this whole period.
@ernietedeschi one big reason for recent monthly deficits tracking lower is a reversal of the pharma and gold front running -- take that out and there isn't much of a trend (may be one starts ) in August

@ernietedeschi The the dollar index may just be v the g-10 (I don't use the WSJ index) and pretty sure it isn't inflation adjusted. BIS real is the gold standard and it shows to me a v. strong dollar (real matters for trade, is what goes into the fed model, etc)

@ernietedeschi the 16-20 level of the dollar led to a clear fall in non-oil exports as a percent of GDP so I would describe even that level as "strong" relative to the fundamentals of the traded economy (not consistent with a stable trade deficit over time). To me still in v strong USD land
@Brad_Setser And to be clear, I mean "weakness" relative to last year's level, against conventional expectations where tariffs put upward pressure on the currency's value when there's not proportional retaliation (there are convincing stories about why such strengthening wasn't sustained).
@ernietedeschi unrelated question, for sectors like pharma where there are deals that reduce the actual tariff rate to individual firms to zero, how does your (great) budget lab model calculate the effective rate? seems really difficult to track
@Brad_Setser When the special lower rates are at the country/regional level, e.g. Japan or the EU, we set the lower rate directly and the model handles substitution normally. When it applies to a firm within a country, that's more detail than the model tracks so we have to pro-rate the rate.
@ernietedeschi indeed i wrote a whole blog post in June about why the Trump trade dollar bull thesis didn't work out.