
🧵While markets obsess over Fed cuts and AI bubbles, India is quietly rewriting its credit playbook. The RBI just dropped 22 reforms + 50bps repo cut ahead + ₹77 lakh crore in corporate debt that could reshape the Indian economy. The full picture by @1FinanceHQ Research👇
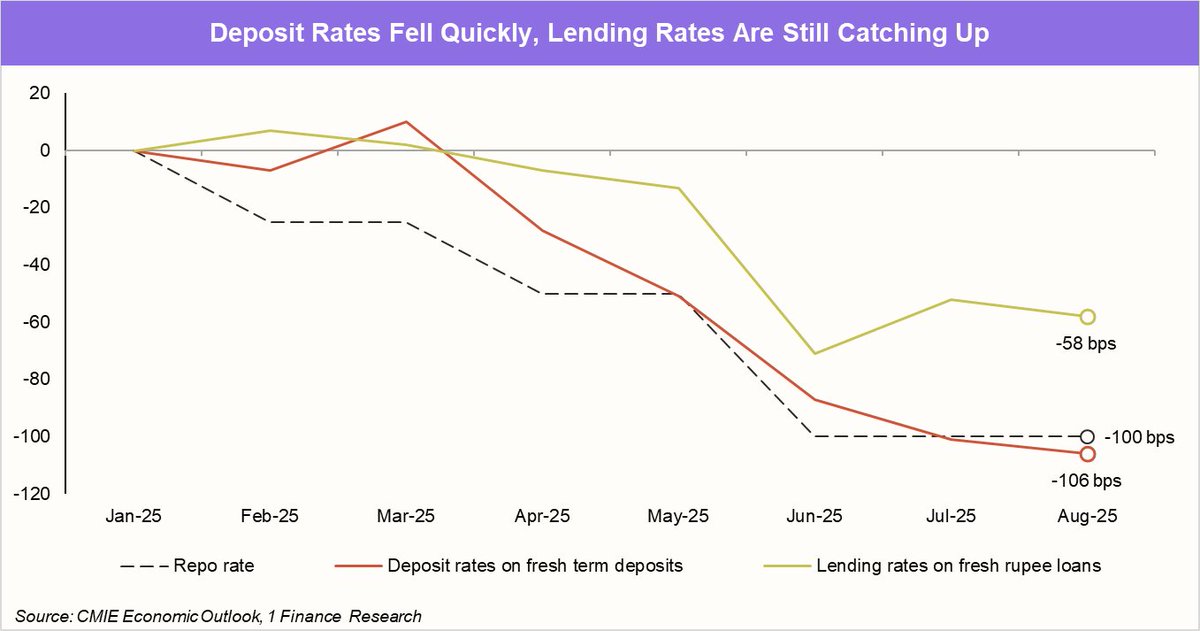
1/ The RBI held rates at 5.5%. Since Feb, they've cut 100 bps. Yet lending rates fell only 58 bps while deposits dropped 106 bps. This transmission gap explains the pause.
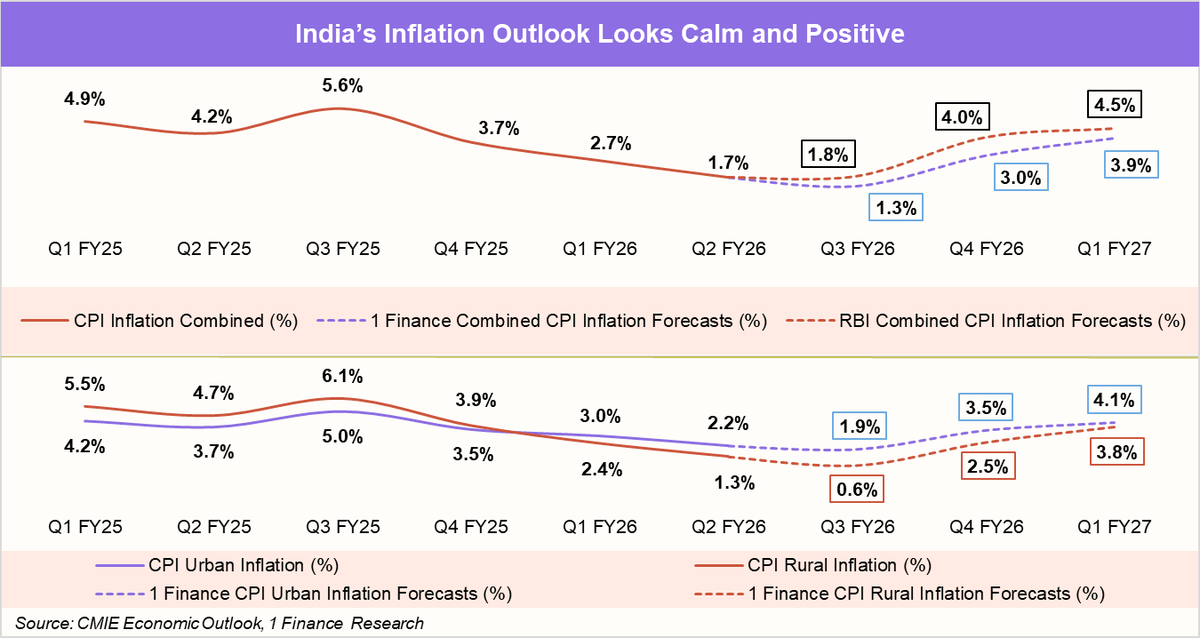
2/ Inflation hit an 8-year low of 1.5% in Sept. RBI forecasts 2.6% for FY26. We see 2.2%, with rural inflation even gentler at 1.7%. This makes a room for another 50 bps cut by end of FY26.
3/ Bank lending stuck at 10% YoY, weakest since 2022. Infrastructure lending hit multi year lows. Credit growth is choking despite rate cuts. Why?

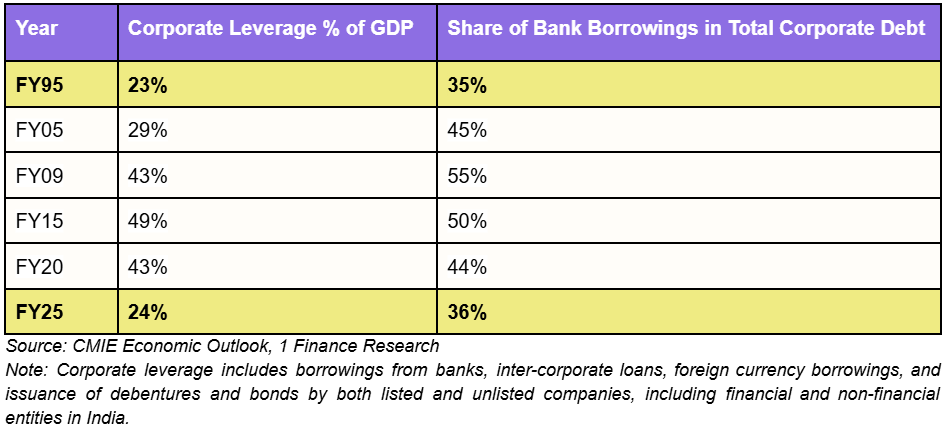
4/ Banks now hold just ₹27L cr of ₹77L cr in total corporate debt. Down to 36%, the lowest in years. Corporates shifted to bonds and ECBs. Banks lost their intermediation role.
5/ The 4 game changers from the 22 reforms announced Oct 1 that no one's talking about. ✅ Large borrower limits raised to 20% of net worth ✅ M&A financing via SPVs ✅ Securities lending up 5x ✅ ECBs expanded to $1B or 300% net worth This should fix India's broken credit

6/ Think of this as India's credit market liberalisation. Just as 1992 opened equity markets to the world, 2025-26 could do the same for credit. Even a 10-15% -from ₹77L of corporate debt- shift back to banks could add ₹8-11 lakh crore in fresh lending capacity.
7/ But here's the risk no one's pricing in: Corporate leverage is healthy at 24% of GDP (same as 1995). But concentration risk is rising. More loans to fewer large borrowers = less diversification. If defaults spike during a downturn, banks face huge asset-liability mismatch.
Adding, M&A financing + real estate ECBs = potential vulnerabilities. Banks need ~10% Tier I capital cushion for riskier activities. Relaxed norms for loans against securities are risky too. If share prices fall and borrowers can't pledge more collateral. Losses mount quickly.
8/ So what does this mean for your portfolio? Equity➡︎M&A activity likely to surge in fragmented sectors like manufacturing, textiles, chemicals. Large-caps benefit most. Debt➡︎Lock in medium-duration exposure now. Inflation at 8-year lows won't last forever.

9/ Growth outlook: Q1 FY26 GDP hit 7.8% Driven by rural consumption + front-loaded govt capex. But momentum moderates through H2. We see FY26 GDP at 6.8% (in line with RBI), peaking in Q2, then easing.
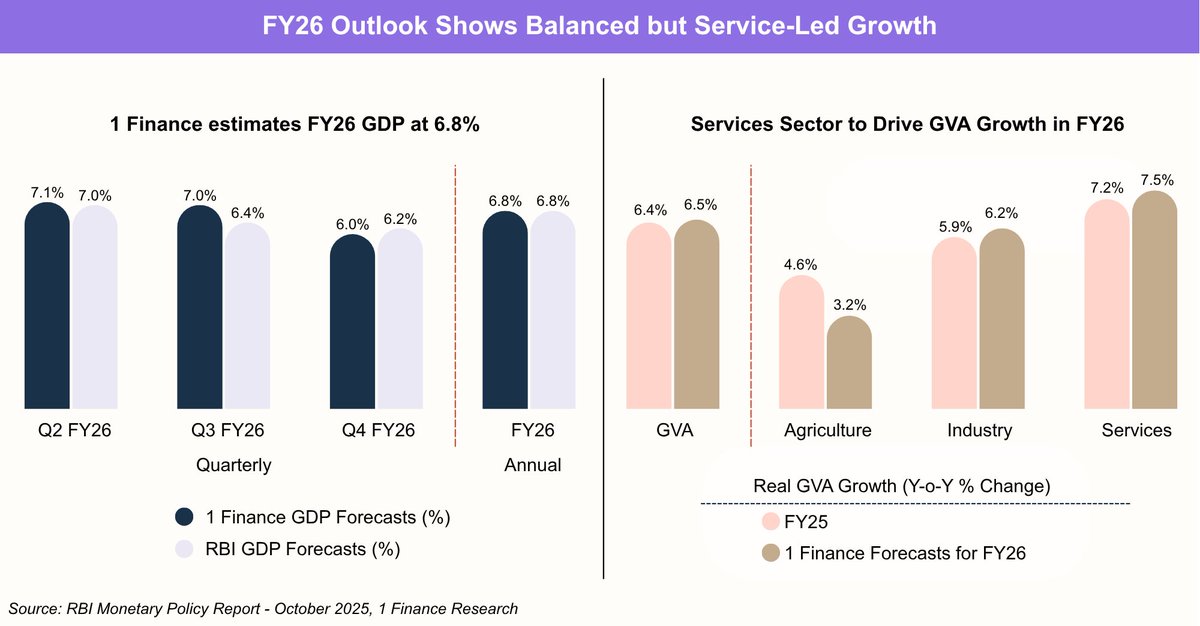
Continuing, Services will drive GVA growth at 7.5%. Agriculture recovering but industry subdued. This is consumption-led growth, not investment-led.
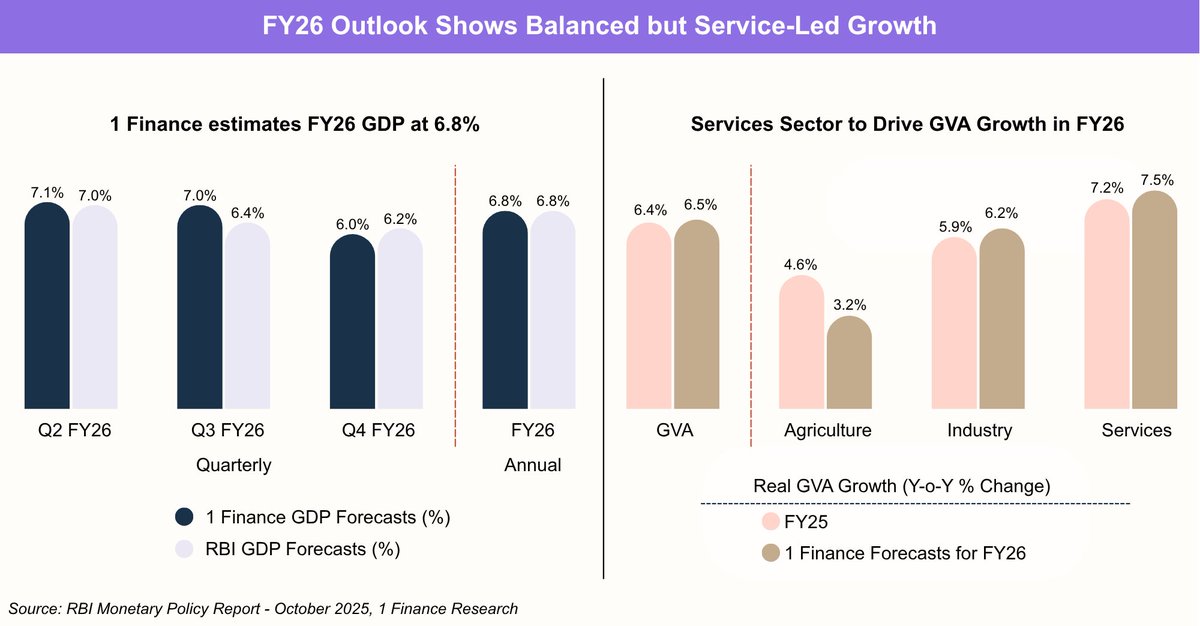
This is balanced, service-led growth with falling inflation, moderate leverage, rising liquidity. These 22 reforms won't make headlines like a repo cut. But they could define the next decade of India's credit markets...🪡 Visit India Macro Indicators for more: